How to Calculate a Mortgage Payment: A Simple Guide
Introduction
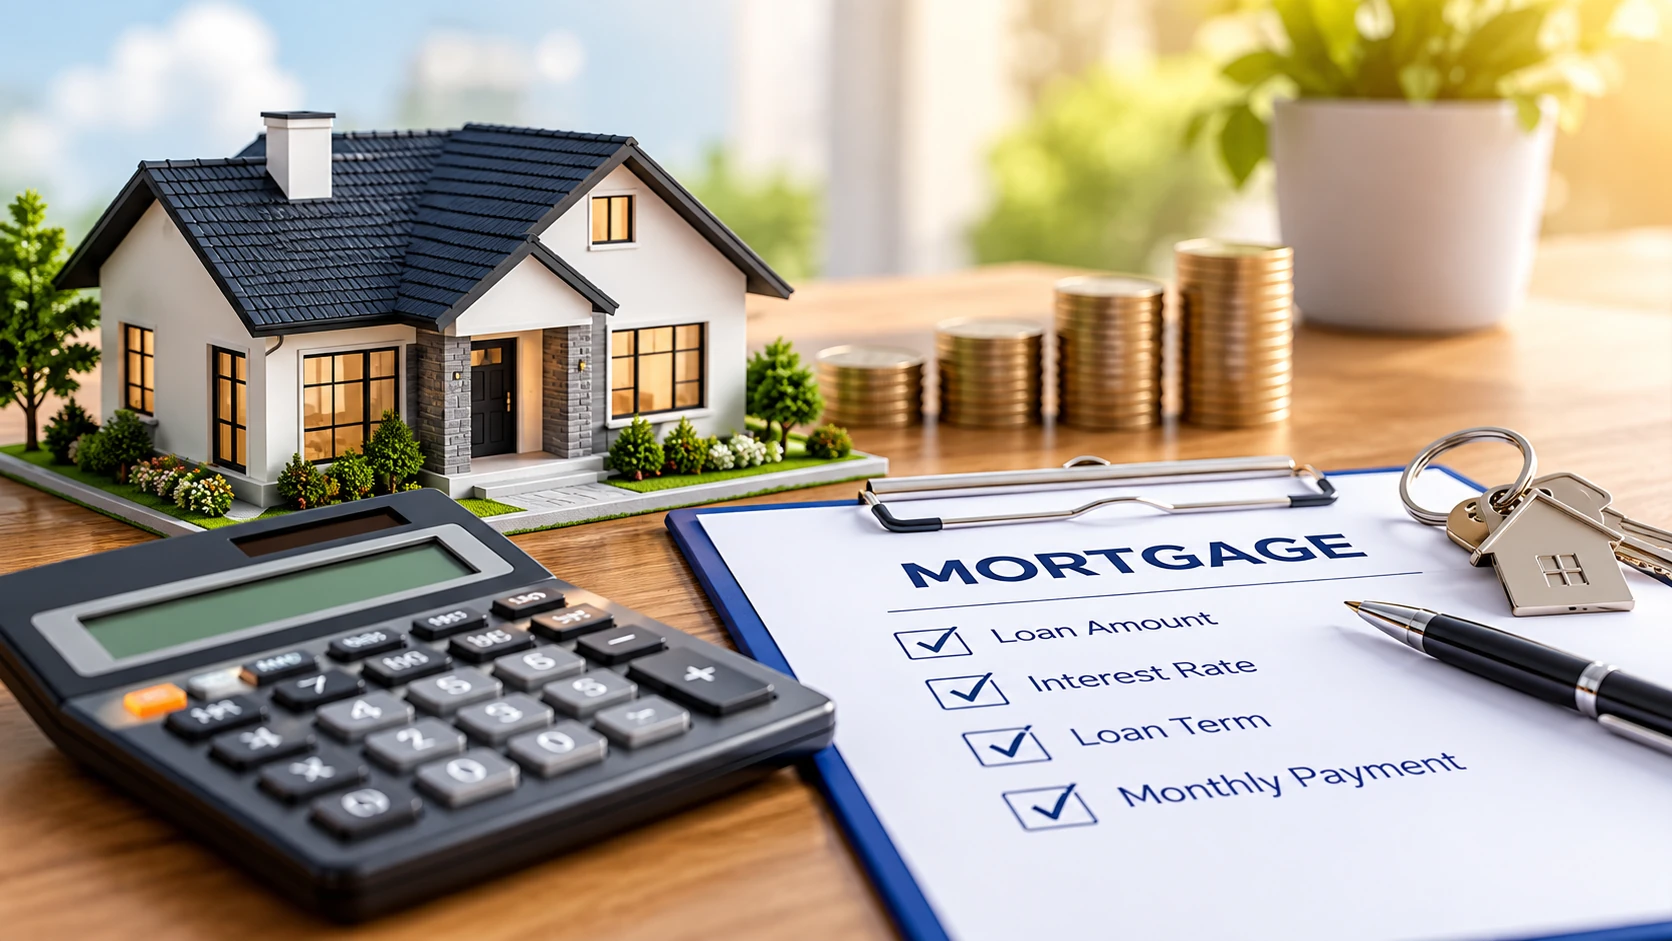
A mortgage is one of the biggest financial commitments many people make, so understanding how mortgage payments are calculated can make it easier to compare loan options and plan a budget. Our Mortgage Calculator can quickly estimate your monthly payment, total payment, and total interest using your loan amount, interest rate, and loan term.
What Is a Mortgage Payment?
A mortgage payment is the amount you pay toward your home loan on a regular basis. For a standard fixed-rate mortgage, the payment primarily consists of principal and interest.
The principal is the amount you originally borrowed, while interest is the cost charged by the lender for borrowing the money.
Depending on the mortgage, your actual housing payment may also include property taxes, homeowners insurance, mortgage insurance, or other costs.
How Is a Mortgage Payment Calculated?
A standard fixed-rate mortgage uses a formula based on three main factors:
- Loan amount
- Interest rate
- Loan term
The standard formula is:
M = P × [r(1 + r)ⁿ] ÷ [(1 + r)ⁿ − 1]
Where:
- M = Monthly payment
- P = Principal loan amount
- r = Monthly interest rate
- n = Total number of monthly payments
The annual interest rate is divided by 12 to get the monthly interest rate, and the number of years in the loan term is multiplied by 12 to determine the total number of monthly payments.
Mortgage Payment Example
Suppose you borrow $300,000 at an annual interest rate of 6% for 30 years.
The monthly interest rate is:
6% ÷ 12 = 0.5%
The total number of payments is:
30 × 12 = 360 payments
Using the mortgage formula, the estimated monthly principal-and-interest payment is approximately:
$1,798.65
Over the full 30-year term, the estimated total payment would be approximately $647,514.57, including about $347,514.57 in interest.
This example does not include property taxes, insurance, or other mortgage-related costs.
What Factors Affect Your Mortgage Payment?
Several factors can change the amount you pay each month.
Loan Amount
A larger loan generally results in a higher monthly payment because you are borrowing more money.
Interest Rate
The interest rate has a significant effect on your mortgage cost. A higher rate generally means a higher monthly payment and more interest paid over the life of the loan.
Loan Term
A longer loan term can reduce your monthly payment because the balance is spread across more payments. However, it can also result in more total interest.
Down Payment
A larger down payment reduces the amount you need to borrow, which can lower your monthly payment and total interest.
How to Calculate a Mortgage Payment
You can calculate an estimated mortgage payment manually using the standard formula, but doing so can be time-consuming.
With a Mortgage Calculator, you only need to enter your loan amount, annual interest rate, and loan term. The calculator performs the calculation automatically and shows your estimated monthly payment, total payment, and total interest.
This makes it easier to compare different loan scenarios.
Monthly Payment vs. Total Mortgage Cost
Your monthly mortgage payment and your total mortgage cost are not the same thing.
A lower monthly payment may look attractive, but if it comes from a longer loan term, you could pay significantly more interest over time.
For example, extending a mortgage from 15 years to 30 years can reduce the monthly payment but may substantially increase the total interest paid.
That’s why it is useful to look at both the monthly payment and total interest when comparing mortgage options.
How a Mortgage Calculator Can Help
A mortgage calculator can help you:
- Estimate monthly payments
- Compare different interest rates
- Compare different loan terms
- Estimate total interest
- Understand the long-term cost of borrowing
- Plan a potential home-buying budget
You can also change one value at a time to see how it affects the overall cost of the loan.
Common Mortgage Calculation Mistakes
Focusing Only on the Monthly Payment
A lower monthly payment does not necessarily mean a cheaper mortgage. Always consider the total amount paid and total interest.
Forgetting the Interest Rate
Even a relatively small difference in interest rates can make a significant difference over a long mortgage term.
Ignoring the Loan Term
The length of the mortgage affects both your monthly payment and the total interest you pay.
Forgetting Additional Costs
A basic mortgage calculation may not include property taxes, insurance, mortgage insurance, lender fees, or other costs.
Frequently Asked Questions
Find quick answers to common questions about mortgage payments, interest rates, loan terms, and home financing.
What is a mortgage payment?
A mortgage payment is the amount you pay regularly toward a home loan. It typically includes principal and interest. Depending on the loan, taxes, insurance, and other costs may also be included.
How is a mortgage payment calculated?
A mortgage payment is calculated using the loan amount, annual interest rate, and loan term. The standard mortgage formula uses the principal, monthly interest rate, and total number of monthly payments to determine the monthly payment.
What is the formula for calculating a mortgage payment?
The standard mortgage payment formula is P × [r(1 + r)ⁿ] ÷ [(1 + r)ⁿ − 1], where P is the loan principal, r is the monthly interest rate, and n is the total number of monthly payments.
Does a longer mortgage term lower the monthly payment?
Generally, yes. A longer mortgage term spreads the loan repayment over more months, which usually reduces the monthly payment. However, a longer term can result in paying more total interest over the life of the loan.
Does a higher interest rate increase my mortgage payment?
Yes. A higher interest rate generally increases your monthly mortgage payment and the total amount of interest paid over the life of the loan.
Does a mortgage calculator include taxes and insurance?
The uPercentage Mortgage Calculator calculates the principal and interest portion of your mortgage payment. Property taxes, homeowners insurance, mortgage insurance, and other additional costs are not included in the calculation.
What happens if the mortgage interest rate is 0%?
If the interest rate is 0%, the loan amount is simply divided by the total number of monthly payments. There is no interest charged, so the total payment is equal to the original loan amount.
Can I use a mortgage calculator for different loan amounts?
Yes. You can enter different loan amounts, interest rates, and loan terms to compare potential monthly payments and total interest costs. This can help you evaluate different mortgage options.
Are mortgage calculator results exact?
Mortgage calculator results are estimates based on the loan amount, interest rate, and loan term you enter. Actual mortgage costs may vary because of taxes, insurance, fees, lender terms, and other expenses.
Can I use the uPercentage Mortgage Calculator for different currencies?
Yes. The calculator works with numerical values, so you can use it for different currencies. Simply enter the loan amount using the currency you are working with and interpret the results in that same currency.
Can I compare different mortgage terms with this calculator?
Yes. You can calculate your payment using different loan terms, such as 15, 20, or 30 years. Comparing the results can help you understand how the loan term affects your monthly payment and total interest.
Can I calculate my mortgage payment with uPercentage?
Yes. The uPercentage Mortgage Calculator is free to use and can quickly estimate your monthly payment, total payment, and total interest based on your loan details.